Across Johor Bahru social media and car ads, banners promising "Zero Down Payment," "100% Full Loan Guaranteed," and "Drive Home Today with Zero Cash" are everywhere. For fresh graduates, budget-conscious buyers, or workers transitioning jobs, this sounds like the ultimate deal.
🔍 Is It Really a Good Deal?
With over 20 years in JB, Dong Huat Services gives you the transparent reality: while Full Loan financing is legal and widely practiced, it carries higher cumulative interest charges, tighter monthly cash flow, and negative equity risks if not planned wisely.
1. How Dealerships Structure a "Zero Down Payment" Used Car Loan
Under Bank Negara guidelines, car hire purchase loans are capped at 90% of valuation. Full Loan is achieved when the official bank valuation exceeds the dealer's selling price.
Example:
• A 2018 Perodua Myvi has an official bank valuation of RM 42,000;
• The 90% maximum eligible loan limit is RM 42,000 × 90% = RM 37,800;
• If Dong Huat Services sells this vehicle for RM 37,800, the entire purchase price is financed by the lender without requiring a cash down payment from the buyer.
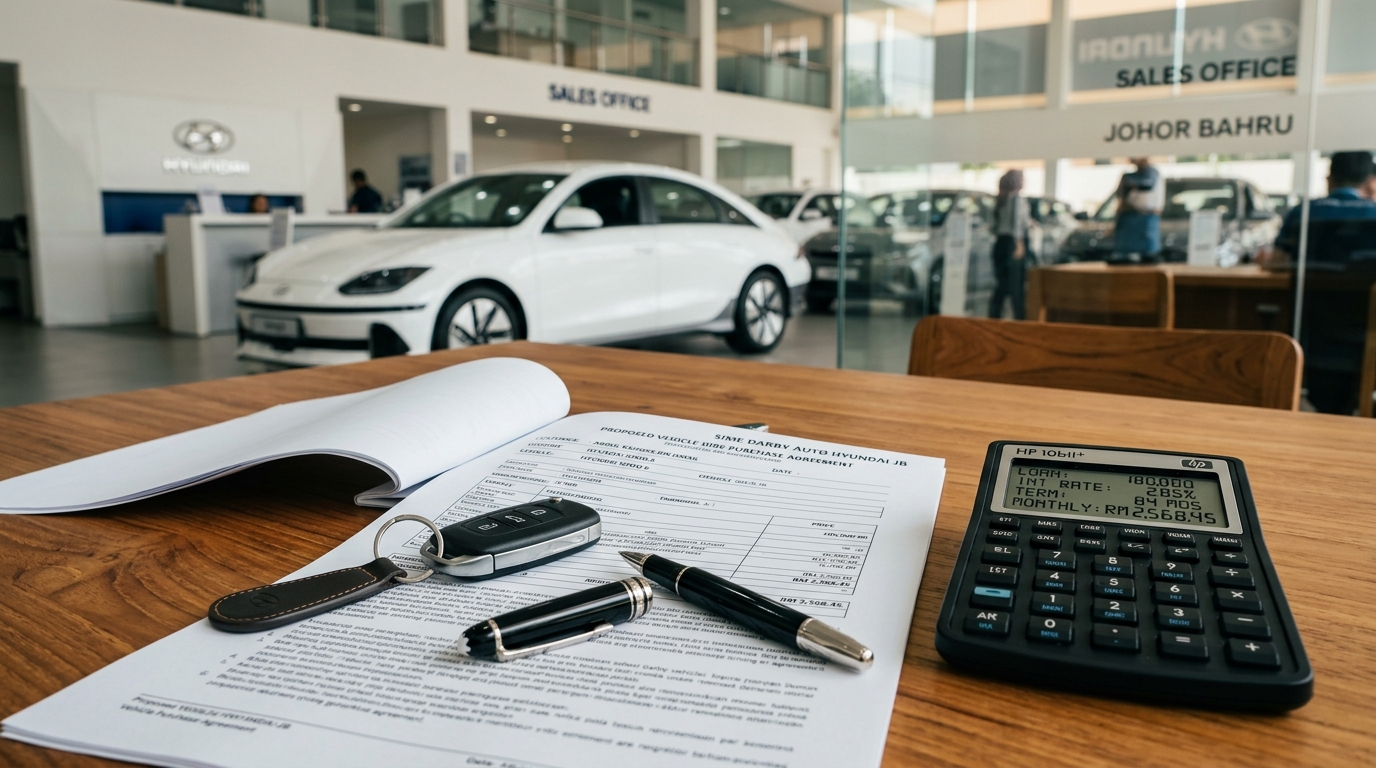
2. Real Calculation Comparison: 10% Deposit vs. Full Loan
| Metric | Option A: 10% Down Payment | Option B: 100% Full Loan |
|---|---|---|
| Cash Down Payment Required | RM 4,000 | RM 0 |
| Financed Principal | RM 36,000 | RM 40,000 |
| Total 7-Year Interest (@ 4.5%) | RM 11,340 | RM 12,600 (+RM 1,260) |
| Estimated Monthly Installment | ~RM 563 / month | ~RM 626 / month (+RM63) |
Frequently Asked Questions (FAQ)
How do dealerships legally structure zero down payment financing on used cars?
Zero down payment is achieved when the official bank valuation of the car exceeds the showroom selling price, allowing the 90% loan ceiling to fully cover 100% of the agreed selling price.
What is the main drawback of a full loan compared to placing a 10% down payment?
You incur higher total interest over the loan tenure, carry a larger monthly commitment, and face negative equity risks should you decide to sell the car within the first two years.
Who benefits the most from choosing a zero down payment loan package?
High-earning cross-border workers who prefer retaining cash liquidity for investments, and fresh jobholders who need immediate transport to commute to work.
Have Questions? Contact Ah Jin
Message us for a free loan eligibility pre-check or test drive.